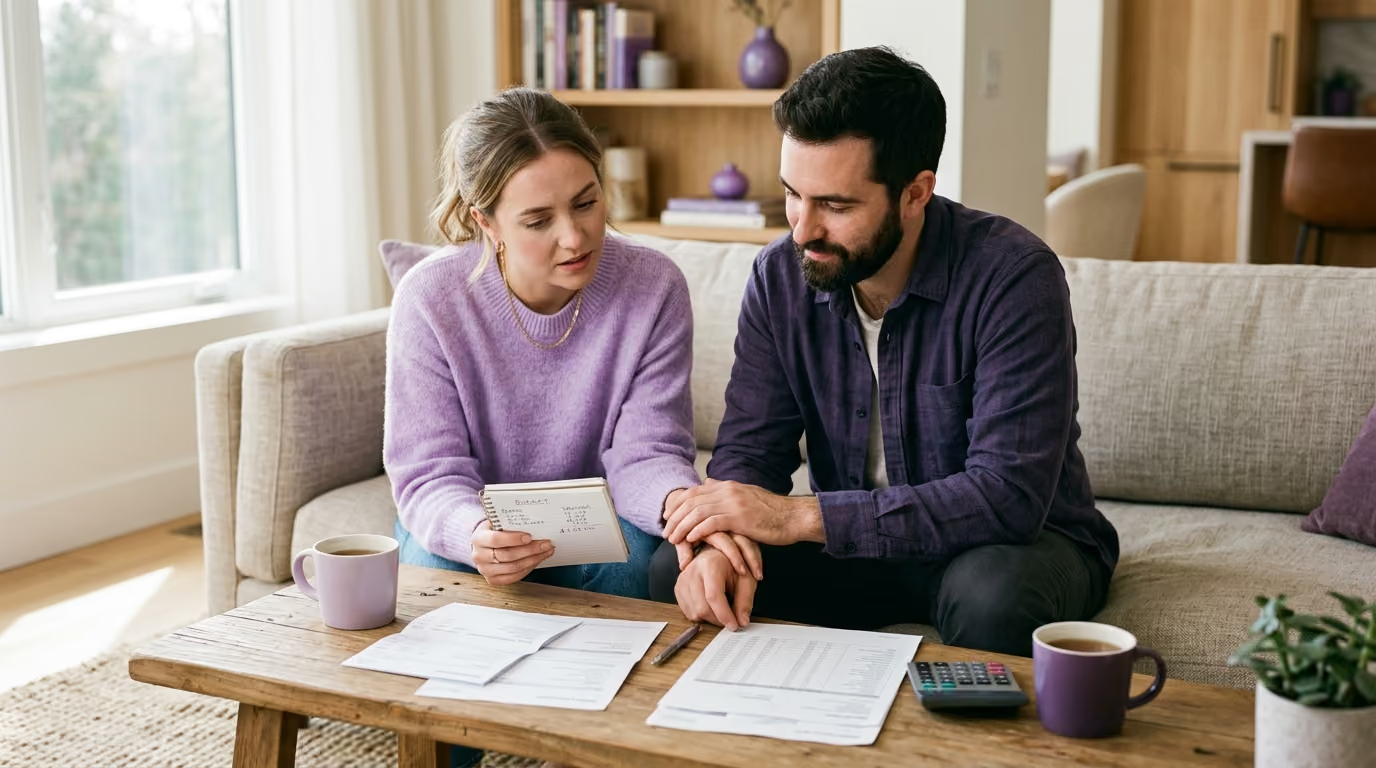
Thirty-one percent of partnered adults report major money conflict, making structured communication tools essential for protecting intimacy and shared relationship goals.


Most couples assume that financial harmony requires matching bank accounts, identical spending habits, or a higher household income. In reality, couples with plenty of money argue just as intensely as those with limited resources. The root of financial tension is rarely the arithmetic on a bank statement.
Instead, money conflicts often reflect deeper relational concerns regarding safety, fairness, control, and recognition. When a partner questions a receipt or worries about a retirement account, they are rarely talking only about currency. They are often asking whether their partner respects their effort, values their future, and protects their emotional safety.
Understanding this dynamic allows couples to protect their emotional and physical closeness during tough economic periods. Staying on the same team does not mean agreeing on every purchase. It means creating a shared process where both partners feel heard, respected, and secure.
To handle money issues effectively, partners must first separate financial stress from financial conflict. Financial stress is the subjective anxiety, worry, or material strain caused by external economic circumstances. Financial conflict, by contrast, is the interpersonal disagreement between partners about how money is handled, prioritized, or discussed.
A couple can experience severe financial stress without fighting. For instance, two partners may face rising living costs with mutual empathy, treating the shortfall as a shared external challenge. Conversely, a couple with high earnings can experience intense financial conflict if one partner makes unilateral purchases or dismisses the other partner's desire for savings.
Researchers study these dynamics through two primary mechanisms known as spillover and crossover. Spillover occurs when an individual's financial anxiety drains their personal patience, energy, and mood. That personal exhaustion makes ordinary daily interactions feel heavier and more irritating.
Crossover happens when that individual stress begins to affect the partner directly. A partner who does not manage the daily bills can still feel the tension entering the home. In a study of romantic couples, baseline financial stress predicted both an individual's relationship strain and their partner's relationship strain.
Research published through the American Psychological Association highlights how persistent economic strain alters marital interactions. Daily financial strain frequently triggers demand and withdraw communication patterns. In this cycle, one partner aggressively pushes for financial changes while the other withdraws into silence or defensiveness. Over time, these daily friction points wear down relationship satisfaction.
Addressing money problems requires recognizing whether you are confronting a resource problem, a communication problem, or both. Treating an external economic shock as a character flaw in your partner only deepens the divide. Recognizing the difference helps couples direct their energy toward solving the problem together rather than attacking each other.
Financial arguments carry heavy psychological weight because money connects to survival, autonomy, and self-worth. In a 2014 survey by the American Psychological Association, 31 percent of partnered adults identified money as a major source of conflict. The same survey noted that money arguments tend to be longer, more intense, and harder to resolve than arguments about other sensitive topics.
A 2023 study published in the National Library of Medicine examined the specific topics couples argue about. The researchers analyzed hundreds of reported conflicts and grouped recurring disputes into two master categories: fairness and responsibility.
Fairness concerns center on balance, equity, and mutual consideration. These disagreements often involve how partners divide shared bills, handle income disparities, or recognize unpaid household labor. When one partner feels they give more than they receive, resentment builds quickly.
Responsibility concerns center on dependability, prudence, and accountability. In the 2023 study, perceived irresponsibility was the most frequently coded conflict theme. These disputes involve concerns about impulse spending, accumulating debt, failing to budget, or breaking financial commitments.
The study identified eight distinct disagreement themes that frequently appear in committed relationships:
This includes frustration over impulsive buying, inadequate savings, recurring debt, or failing to follow agreed spending guidelines. One partner views the other as reckless, while the other may feel constantly judged or micro-managed.
Disagreements in this category involve career choices, job loss, earning potential, or long working hours. The 2023 study found that conflicts over jobs and income were closely associated with lower relationship satisfaction.
This theme involves perceived imbalances between what each person brings to the household. It includes disputes where one partner earns less or where one partner performs the vast majority of unpaid domestic work and childcare.
These conflicts focus on the mechanics of everyday expenses. Partners may argue over who covers utilities, groceries, rent, or recurring subscriptions, especially when their individual incomes differ significantly.
Major life events frequently generate financial friction. Large home repairs, vehicle replacements, medical bills, or expensive vacations force couples to make high-stakes decisions under time pressure.
Couples frequently disagree on whether their finances should be pooled, kept separate, or managed through a hybrid model. The 2023 study found that account structure alone did not predict which conflict themes arose between partners.
Every adult brings a personal money history into a relationship. One partner may view money primarily as a tool for current enjoyment, while the other views it as essential armor against future catastrophe.
These disputes occur when one partner makes a significant financial commitment without consulting the other. The issue is rarely just the cost. It is the feeling of exclusion and broken trust.
The 2023 study authors noted important limitations to their findings. Their data relied partly on anonymous online forums and partly on retrospective self-reports from mostly married, economically stable participants. Nonetheless, these eight themes illustrate that money arguments are rarely about raw numbers alone.
Financial anxiety directly impacts emotional, physical, and sexual closeness. When the brain perceives a threat to financial security, the nervous system shifts into a chronic stress response. This state of low-grade biological alarm reduces the patience, playfulness, and emotional bandwidth required for romance.
A study on couples during the COVID-19 pandemic demonstrated the complex link between financial stress and intimacy. When couples experienced rising financial stress, their relationship conflict increased. However, when financial stress decreased, couples did not automatically experience an instant rebound in happiness and closeness.
Relational connection requires intentional care, not just the removal of economic pressure. When financial survival consumes all of a couple's conversations, practical administration replaces connection. Every conversation risks turning into a stressful negotiation over bills, schedules, and cutbacks.
Over time, this administrative burden drains the romantic atmosphere from a home. Partners begin to see each other as coworkers running a struggling household enterprise rather than lovers sharing a life. Developing strong couples communication strategies allows partners to establish boundaries that protect their private time together.
Chronic financial stress also affects physical well-being and sexual function. Cortisol elevation and sleep deprivation diminish energy, lower sexual desire, and make physical affection feel like another exhausting demand. When one partner interprets this withdrawal as romantic rejection, the emotional distance widens.
Intimacy thrives on perceived partner responsiveness, which means feeling understood, validated, and cared for by your mate. In the 2023 conflict study, disagreements involving perceived irresponsibility were strongly linked to lower partner responsiveness. When people feel judged or dismissed by their partner, they naturally protect themselves by pulling away physically and emotionally.
Staying connected requires couples to decouple their financial administration from their romantic life. Financial difficulties are hard enough without letting them dismantle the mutual affection that brought you together.
A healthy relationship balances individual autonomy with shared accountability. However, confusion often arises regarding where personal financial privacy ends and financial deception begins.
Academic researchers define financial infidelity as engaging in any financial behavior that a partner would reasonably disapprove of, combined with the deliberate choice to conceal it. It is not defined simply by having a separate bank account or buying personal items. The defining element is the intentional concealment of transactions that affect the shared partnership.
Common examples of financial infidelity include:
Prevalence estimates vary depending on how surveys define deceptive behavior. A 2021 survey by the National Endowment for Financial Education found that 43 percent of adults with combined finances admitted to some form of financial deception. Earlier academic reviews reported self-admission rates between 13 and 22 percent.
These broad survey figures should not be viewed as an absolute measure for every relationship. However, they demonstrate that financial secrecy is a widespread challenge in adult relationships.
It is vital to distinguish between healthy privacy and harmful deception. In many relationships, partners agree that each person retains a personal allowance to spend with complete autonomy. That is healthy privacy because both partners understand and consent to the boundary.
Financial infidelity occurs when that boundary is breached through deceit. Discovering hidden debt or secret accounts damages trust in the exact same manner as emotional infidelity. The hurt partner feels blindsided, unprotected, and unable to make informed choices about their own future.
Rebuilding trust after financial deception requires absolute transparency. It requires opening all financial records, acknowledging the breach of trust, and agreeing on clear boundaries for future disclosure.
When money tensions run high, spontaneous conversations often degenerate into defensive arguments. Couples need a deliberate, low-risk process to discuss financial issues constructively.
Drawing from research on dyadic coping and clinical relationship guidance, this seven-step framework helps partners move from mutual blame to collaborative problem-solving. It treats money management as a shared project rather than an interpersonal courtroom.
Begin by defining the practical issue using neutral, descriptive language. Focus on the situation rather than assigning character flaws or personality labels.
Starting with facts rather than accusations prevents the other person's nervous system from immediately shifting into defensiveness. It frames the financial balance as the challenge to be solved together.
Every money disagreement contains three distinct layers. Slowing down the conversation to examine each layer clarifies what is really happening.
One partner may view a growing emergency fund as essential safety, while the other views it as unnecessary deprivation. Clarifying these layers prevents partners from talking past each other.
In money arguments, partners often dig into rigid positions. One demands combined accounts while the other insists on total separation.
Rather than arguing over rigid stances, ask what need that position satisfies. Does separate money represent personal independence and safety? Does a joint account represent unity and mutual trust? Understanding the underlying need makes it possible to find flexible compromises that satisfy both individuals.
When a partner expresses financial anxiety, the natural temptation is to immediately propose budgets, spreadsheets, or spending cuts. However, research into relationship coping shows that immediate problem-solving can backfire if a partner feels unheard.
A study analyzing daily diary reports from couples found that emotion-focused coping buffered the negative effects of financial stress. Offering reassurance and validation helped reduce relationship strain. Conversely, jumping straight into analytical problem-solving without empathy often intensified negative emotions.
Take time to say: "I understand why this feels overwhelming, and we are going to handle this together." Once emotional safety is established, practical planning becomes far more effective.
Broad arguments about money rarely produce practical outcomes. Transform vague frustration into a specific, bounded question that requires an answer today.
Narrowing the scope turns an overwhelming crisis into manageable tasks. It allows the couple to experience small, shared victories that rebuild confidence.
Many couples stall because they believe every financial agreement must be permanent. That belief raises the stakes and creates resistance.
Instead, agree to test an arrangement for a defined trial period, such as sixty or ninety days. For example, try a new grocery allocation or a revised bill split for two months, then schedule a date to review how it worked. Framing decisions as experiments reduces anxiety and encourages flexible collaboration.
If heart rates rise and voices escalate, continuing the conversation will only cause relational damage. Take a structured time-out before destructive words are spoken.
An effective pause requires two essential commitments:
A pause is not avoidance. It is a biological necessity that allows your nervous systems to cool down so you can return to the conversation as allies.
Theoretical models are useful, but relationship dynamics play out in complex, messy circumstances. The following illustrative scenarios demonstrate how common financial friction points can be handled using collaborative communication.
In this scenario, one partner earns significantly more than the other. The higher earner suggests splitting all household bills equally down the middle. The lower earner struggles to pay their half, feeling constantly broke, resentful, and embarrassed to speak up.
The Underlying Issue: This is a dispute over relative contributions and the meaning of fairness. An equal mathematical split does not equal an equitable burden when incomes are heavily unbalanced.
The Collaborative Shift: The couple shifts from a strict fifty-fifty split to a proportional contribution model. They calculate shared expenses based on the percentage of total income each partner brings in. Both partners agree that non-financial contributions to the home hold genuine value, restoring a sense of mutual dignity.
One partner grew up in financial instability and feels profound panic whenever savings drop below a certain threshold. The other partner grew up in a stable home and views money as a resource meant to improve daily life, travel, and personal comfort.
The Underlying Issue: This is a clash of fundamental money values and emotional coping styles. The saver uses accumulation to manage anxiety, while the spender uses purchases to experience joy and freedom.
The Collaborative Shift: Instead of labeling each other as cheap or irresponsible, they establish distinct categories. They automate an agreed monthly transfer to emergency savings to give the saver peace of mind. Simultaneously, they allocate an agreed, guilt-free personal spending allowance to each partner, protecting individual freedom without threatening household stability.
A partner buys an expensive piece of electronics or home equipment without mentioning it beforehand. The other partner discovers the expense on the credit card statement and reacts with fury over the lack of communication.
The Underlying Issue: The core problem is not whether the purchase was affordable. The issue is a one-sided decision that violated expectations of mutual consultation.
The Collaborative Shift: The purchasing partner listens to the boundary violation without making excuses about the necessity of the item. Together, they establish a clear threshold rule. Any personal purchase exceeding an agreed amount requires a brief conversation before the transaction occurs.
A partner discovers that their mate has accumulated significant credit card debt across several hidden accounts. The discoverer feels devastated, questioning whether they can trust anything their partner says.
The Underlying Issue: This is a direct instance of financial infidelity. The concealment threatens the joint security of the household and fractures relational trust.
The Collaborative Shift: The partner with debt takes complete ownership without blaming external circumstances. They lay out all statements, balances, and interest rates in full view. The couple agrees on a structured repayment plan and sets a regular weekly check-in to review balances, rebuilding trust through radical transparency.
A couple facing rising mortgage rates and child expenses spends every evening talking about costs, spreadsheets, and budget cuts. Within months, their affectionate touch, laughter, and sexual intimacy completely vanish.
The Underlying Issue: The cognitive load of financial stress has spilled over into every corner of their shared life, pushing out intimate connection and relationship vitality.
The Collaborative Shift: The couple creates a strict boundary around financial conversations. They establish a single forty-five-minute financial meeting every Sunday afternoon. Outside that scheduled time, discussing bills is off-limits, freeing up evenings for rest, physical affection, and emotional reconnection.
Financial dynamics do not exist in a vacuum. They shift continuously as individuals navigate midlife, changing biology, and complex family responsibilities.
During midlife, couples often face the financial pressures of the sandwich generation. They may simultaneously support emerging adult children while caring for aging parents. This dual caregiving responsibility introduces heavy financial obligations that drain emotional and monetary reserves. Understanding these changes within a midlife and aging framework helps couples prepare for inevitable shifts in priority.
Hormonal shifts, menopause, and midlife health changes can also influence energy levels and earning capacity. A health crisis or chronic physical condition introduces unpredictable medical costs alongside physical fatigue. When physical capacity changes, the division of paid and unpaid labor within a household often requires renegotiation.
Unpaid domestic labor remains a major source of invisible financial tension. Managing schedules, caring for family members, and maintaining a home require massive investments of time and energy. When a relationship only validates income brought home in cash, the partner carrying the domestic workload feels deeply undervalued.
Recognizing broad lifestyle and sexual wellbeing factors ensures that partners do not reduce each other to economic production units. A healthy partnership acknowledges that contribution takes many forms beyond a salary figure.
Personal trauma and family background also shape how each partner reacts to financial uncertainty. A person who witnessed parental bankruptcy or volatile arguments over bills will react to minor financial bumps with profound panic. Recognizing your partner's emotional history fosters patience, allowing you to respond with empathy rather than annoyance.
While structured communication frameworks help many couples, some financial situations exceed the scope of self-help strategies. Knowing when to seek qualified outside support protects both your financial future and your relational health.
Couples should consider professional guidance under the following circumstances:
If every conversation about money turns into a screaming match or stonewalling, a licensed marriage and family therapist or financial therapist can provide essential structure. A professional helps uncover the emotional history beneath the conflict without taking sides.
When financial difficulties stem from compulsive gambling, untreated substance use disorders, or severe compulsive shopping, self-guided budgeting will not work. These situations represent health crises that require specialized clinical intervention and addiction recovery support.
If a couple faces potential foreclosure, overwhelming debt collection, or impending bankruptcy, seeking a accredited non-profit credit counselor or certified financial planner is vital. Having an objective third party evaluate the numbers takes the pressure off the relationship.
It is critical to distinguish between symmetrical relationship conflict and coercive control. In a typical relationship disagreement, both partners have voice, agency, and access to resources, even if they disagree on allocations.
Financial abuse, by contrast, is a form of coercive control where one person systematically strips the other of financial independence. Warning signs of financial abuse include:
In situations involving coercion or abuse, generic communication advice about compromise does not apply. The priority must always be safety, autonomy, and consulting appropriate domestic support resources.
For couples experiencing ordinary friction, however, professional support is simply an investment in longevity. Learning to handle money as a unified team transforms one of the greatest sources of marital stress into an enduring foundation for shared trust.
Managing money as a team is an ongoing process of mutual listening and shared adaptation rather than a state of effortless perfection.
Follow Sexential for thoughtful guidance on desire, sexual function, hormones, confidence, relationships and intimacy. Explore new resources and evidence-aware guidance for sexual wellbeing across adulthood.


Explore practical resources on desire, function, hormones, confidence, intimacy and sexual wellbeing.
Read the Blog